Filing a roof claim? Bring proof.
After a storm, your insurance company asks two things: when did it happen, and what does the roof look like? The Claim Pack answers both in one PDF — dated aerial photos of your roof, the documented storm record for your address, and a summary written for your adjuster.
$49, one time. And if there's no documented storm for your address, we won't sell you one — we'll tell you straight, and that's the end of it.
✓ Storm record checked first, free ✓ No documented storm, no sale ✓ PDF emailed to you, ready to send your adjuster
What's in the pack
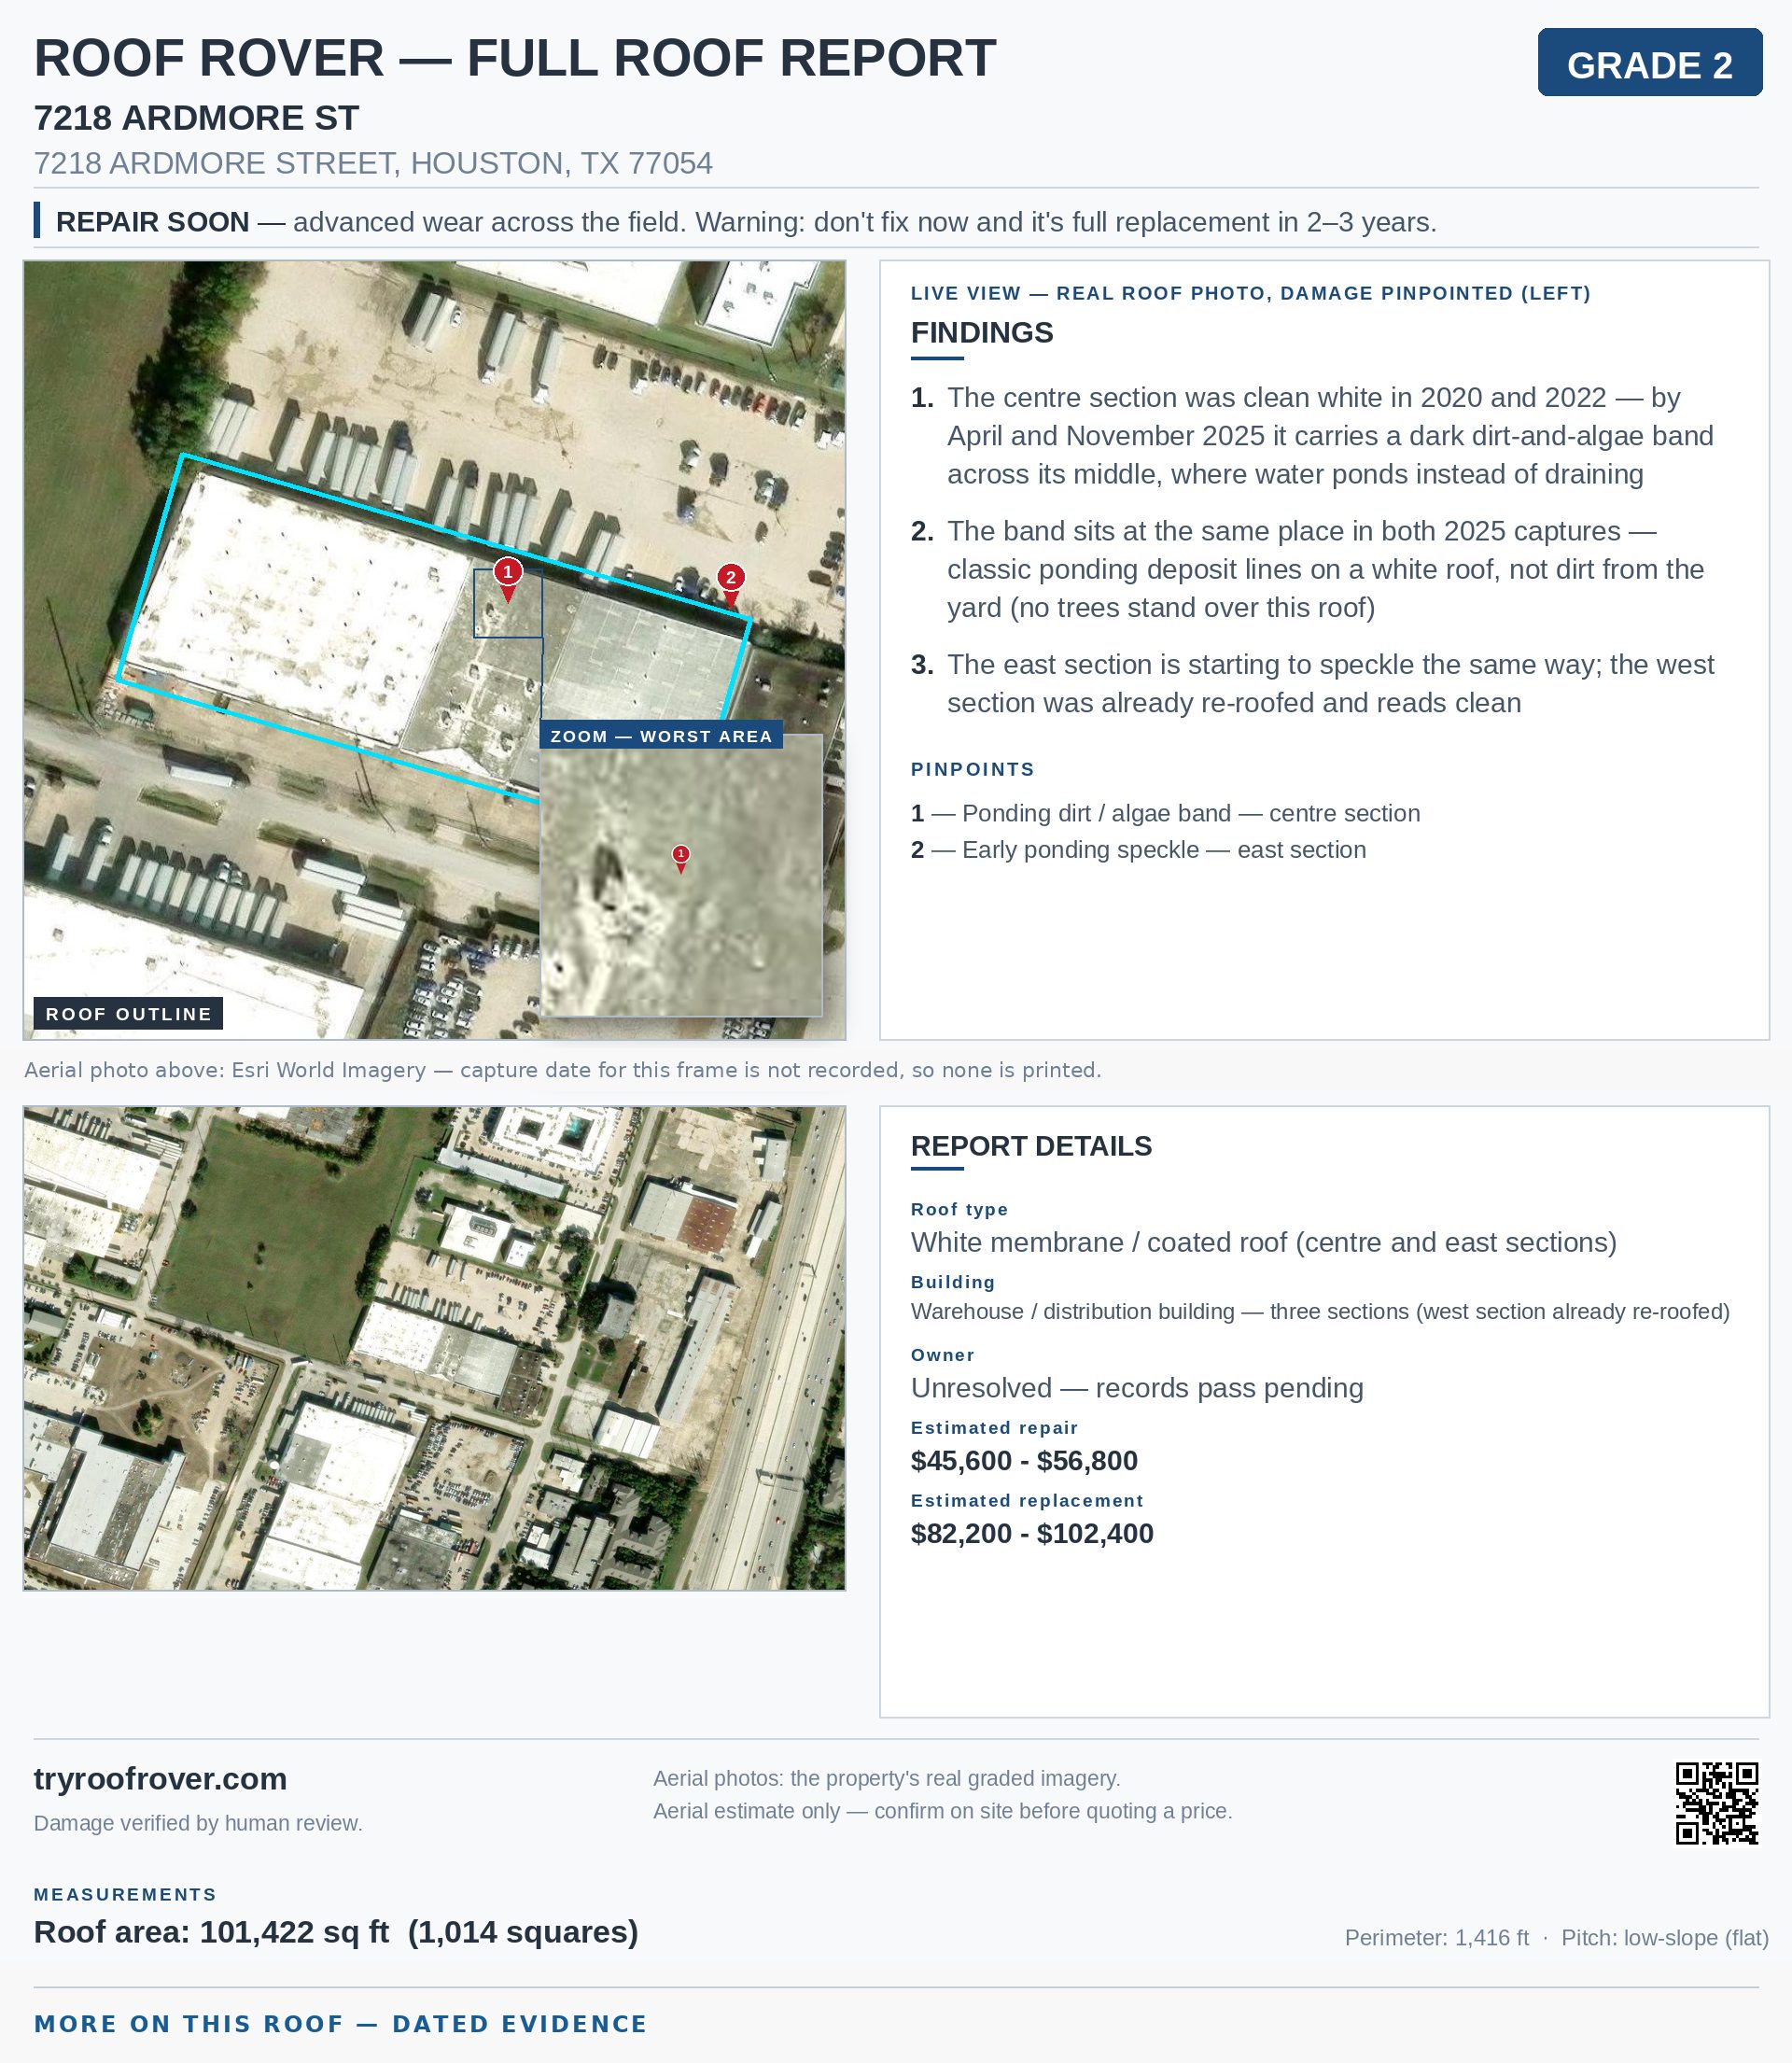
- Your full roof report — photos of your roof with what's wrong marked and measured.
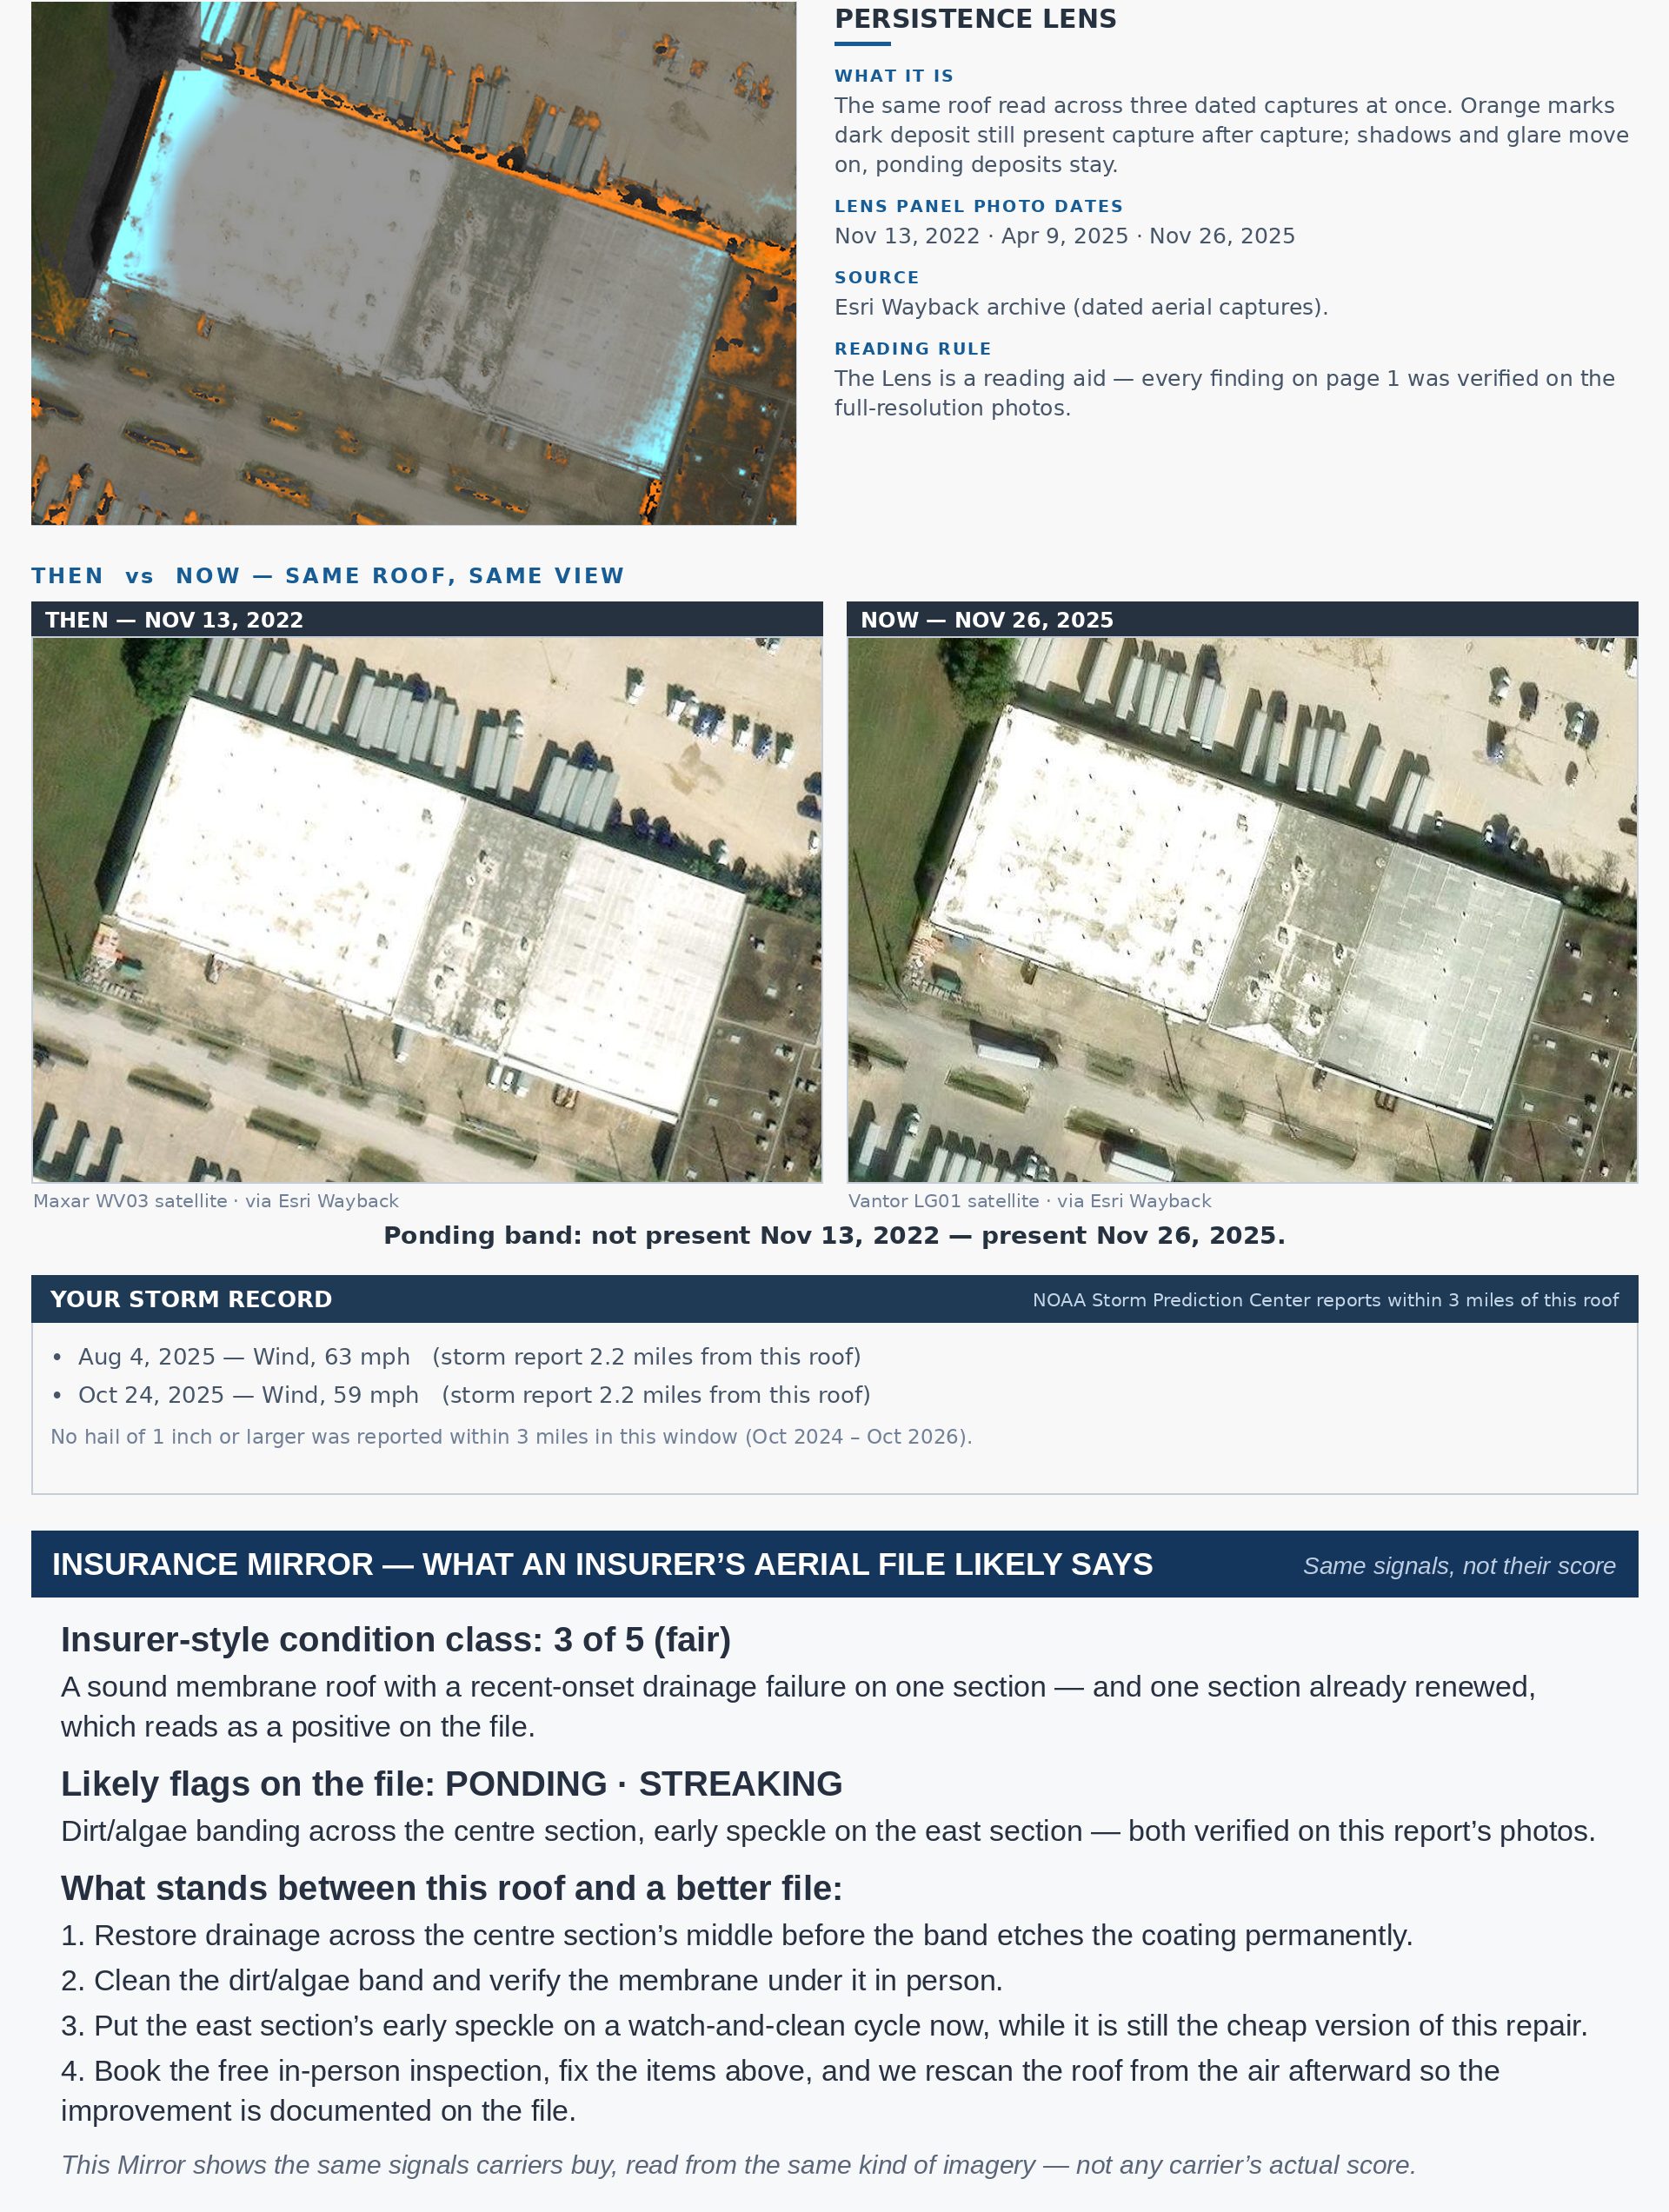
- The dated photo evidence — aerial photos of your roof through the years, every one with its capture date.
- The storm record for your address — the documented storms within 3 miles of your home over the last 2 years.
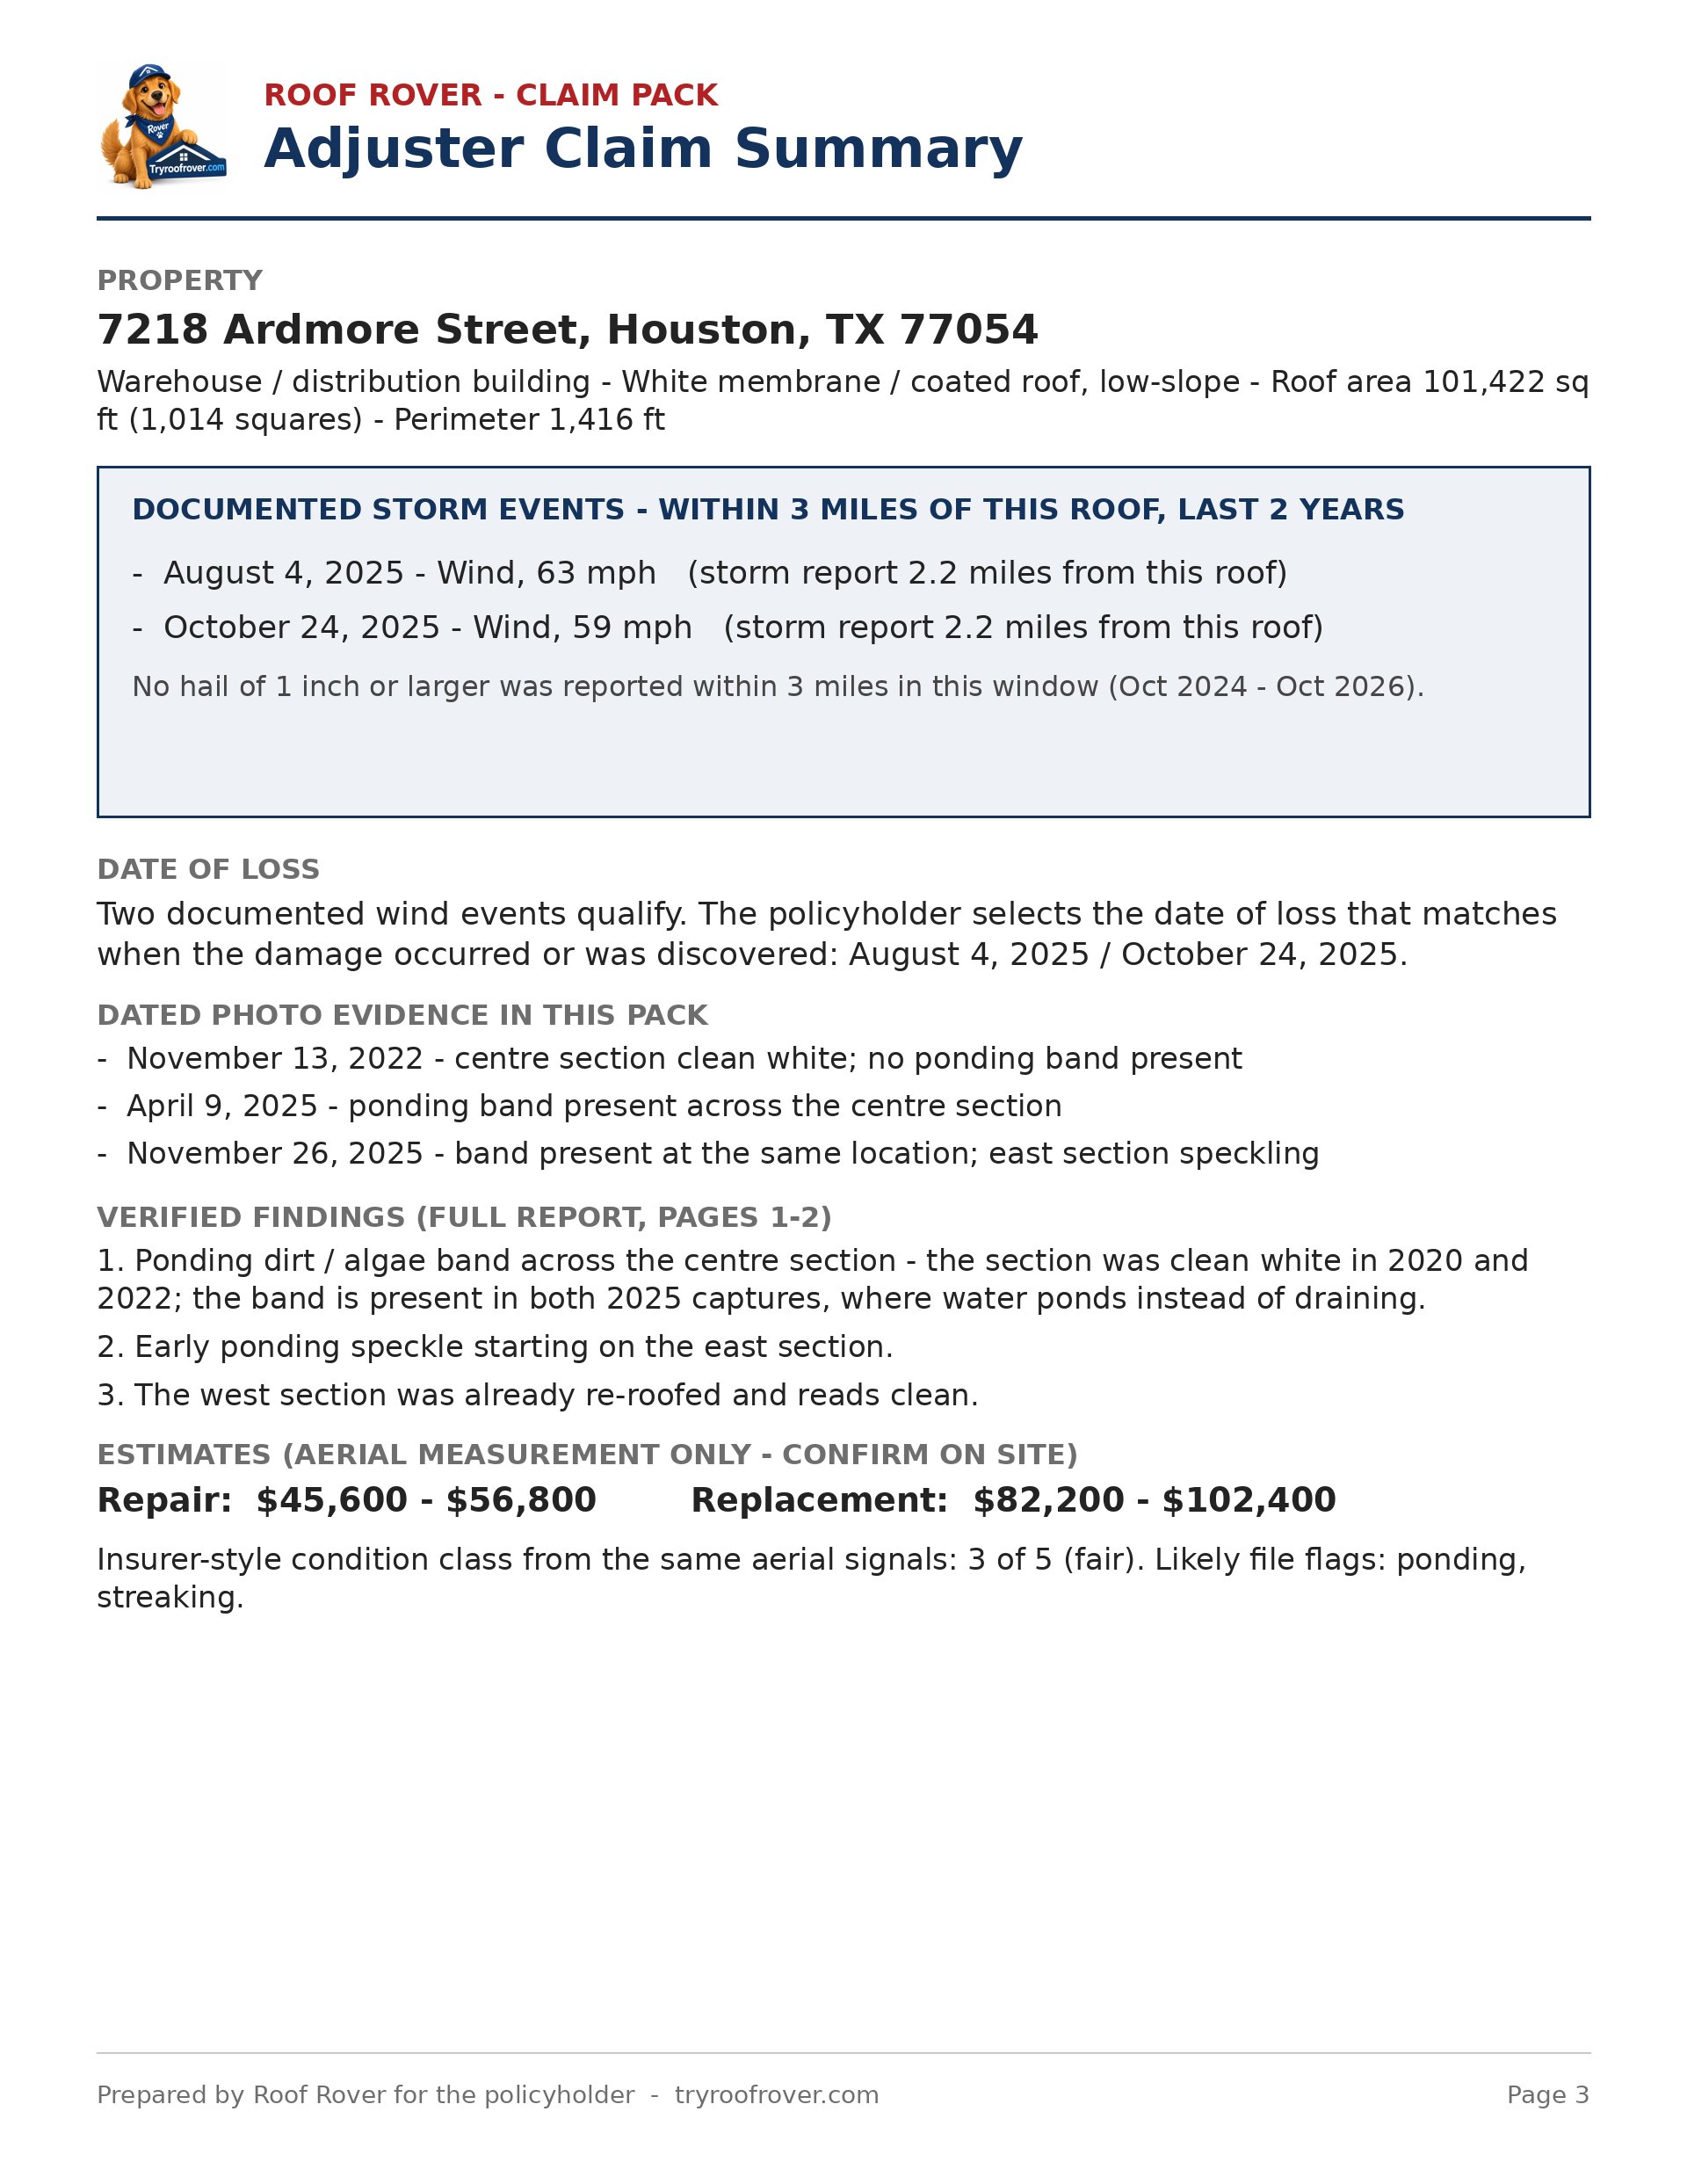
- A one-page summary for your adjuster — the storm, the dates, and what the photos show, in plain English.
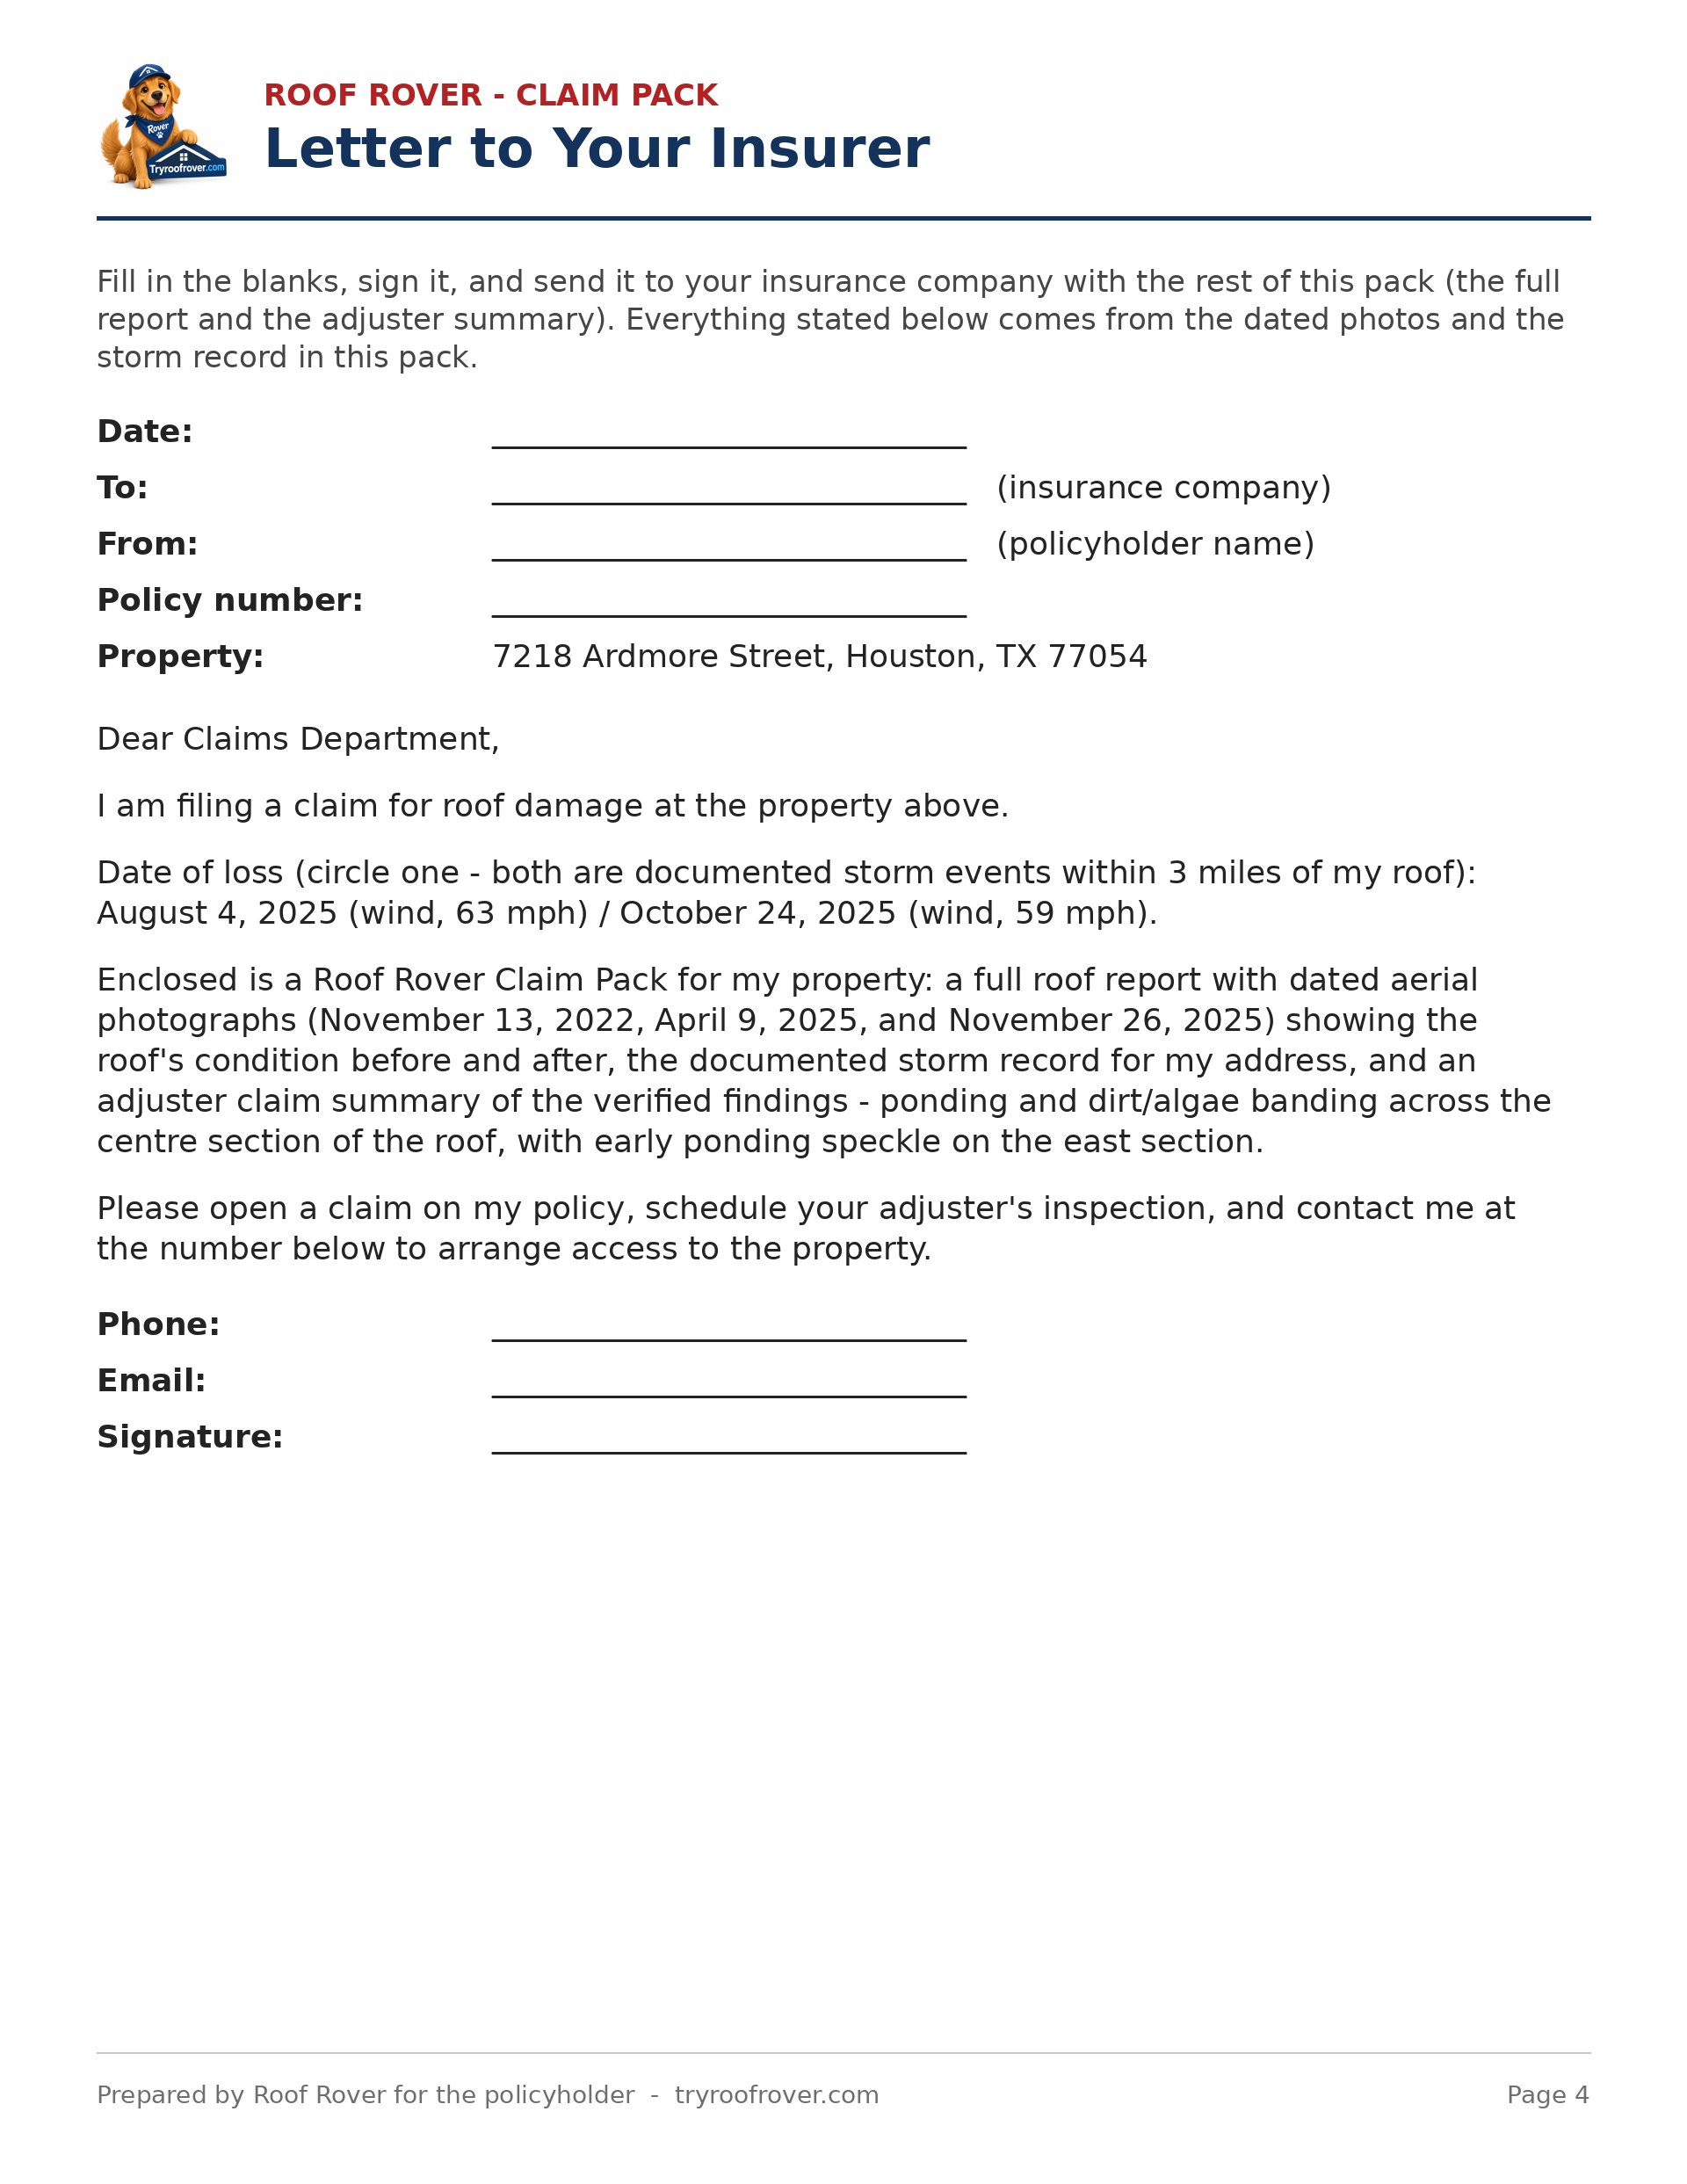
- A cover letter for your insurance company — with the storm date filled in when there's one clear date, and blanks ready for your name and policy number.
See exactly what you get — a real Claim Pack
This is a real Claim Pack, built for a Houston warehouse with two documented wind storms on its record. Your pack is built the same way, for your address — and it's only sold when your address has a qualifying documented storm, the same rule as this one.
How it works
- Enter your address. We check the documented storm record for it first — that check is free. If there's no documented storm for your address, we tell you straight and there's nothing to buy.
- Check out — $49, one time. Paying is what starts your pack: we run the scan for your address and build the full report from it.
- We check the pack before it goes out. If anything in the report doesn't hold up, we hold the pack and fix it instead of sending you a wrong report. The finished pack is then emailed to you, ready to send your adjuster.
The Claim Pack documents what was recorded for your address. It doesn't decide what your policy covers — that's your insurance company's call.